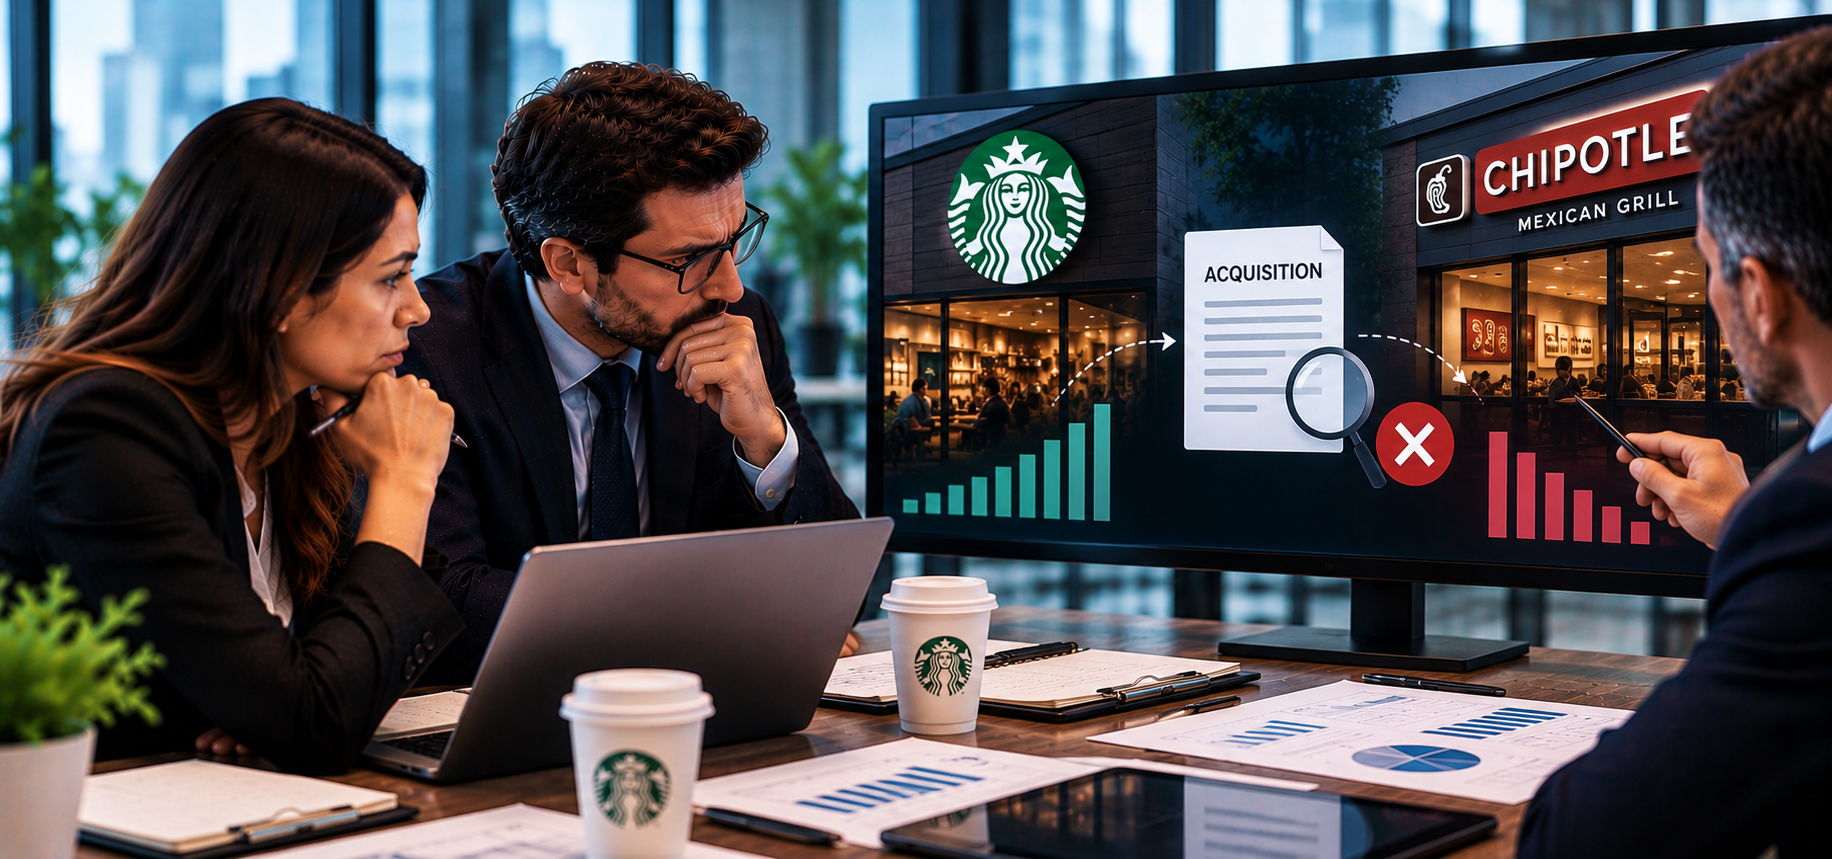
A newspaper report that Starbucks had worked with advisers on a Chipotle bid ended four days later in a flat denial. No offer was made and no deal died. The episode still shows something most CEOs get wrong: exploring a big deal is never private, and it is never free.
On Thursday, October 8, the Financial Times reported that Starbucks had spent recent months working with advisers on a possible takeover of Chipotle Mexican Grill. Chipotle's stock jumped about 6%, to a market value of around $41 billion. Starbucks, worth roughly $107 billion, traded down as much as 3% before closing close to flat. Its first response was the standard one: no comment on rumors, and a reminder that the company was "laser focused" on its turnaround.
On Monday, October 12, it went further. "As a matter of policy, we don't comment on rumors and speculation," a spokesperson said, "but we want to be clear we are not buying Chipotle." Starbucks closed up 1.7%. Chipotle gave back nearly 4%.
Nothing happened, in other words. Something was still spent.
Looking was the defensible part
Much of the early commentary scolded Starbucks for the idea itself: a company mid-repair eyeing what would reportedly have been the largest restaurant acquisition on record. That criticism is too comfortable.
Consider what the target looked like from Brian Niccol's chair. He ran Chipotle for six years before leaving for Starbucks in 2024. Since then Chipotle's shares have fallen by nearly half, and its traffic declined through 2025. An acquirer whose CEO knows the target's kitchens, real estate and failure modes better than its current owners do is about as close to an information edge as M&A gets. A board that forbids management from ever studying a moment like that isn't being disciplined. It's choosing not to know.
So the mistake, if there was one, wasn't the looking. It was the assumption, common to almost every leadership team that commissions this kind of work, that looking happens in private.
What the leak actually said
Starbucks's own plan is working by the measures it chose. In the quarter to June, US comparable sales rose 7.9%, transactions were up 4.2%, and management raised its full-year outlook. The repair isn't finished: adjusted operating margin of 14.4% compares with 16.7% two years earlier, and the shares had gained about half as much as the S&P 500 this year.
That combination is exactly when exploration becomes legible to outsiders. The moment people learn a CEO has had bankers studying a $41 billion target, they ask one question: why now, if the plan is working? Only two answers are available, and neither helps. Either the plan isn't enough, or the leadership has spare capacity the plan doesn't need.
Look at who bid for what. Chipotle's holders priced in the chance of getting their former CEO back. An RBC analyst said investors would likely welcome the deal for exactly that reason, while calling the logic for Starbucks unclear. Starbucks's holders, in effect, voted to keep him. The asset both markets were trading was one executive's attention.
Exploring a deal is an option you hold in private and a signal you send in public. Most CEOs only put the first on the balance sheet.
The four days between "no comment" and "no"
The sequence deserves more attention than the deal. Thursday's response left the door open. Monday's closed it, in writing, on a timetable set by a newspaper rather than by the board, and a few weeks before Starbucks reports its fourth quarter and gives its fiscal 2027 outlook.
A categorical denial is a commitment device. Under the UK Takeover Code, a public statement of no intention to bid is legally binding: the would-be bidder is generally locked out for six months. American companies face no such rule. They are bound only by credibility, which for a CEO in the middle of a turnaround is the scarcer currency. Starbucks has now promised investors that its growth will come from the plan. That is probably the right promise. It just wasn't one it chose to make that week.
Figure 1
Who learns of it | What they hear | What it can cost | What to have ready |
|---|---|---|---|
Investors | The organic plan may not be enough | A discount on the plan; questions about financing and dilution | A one-sentence answer to "why now?" |
The team running the plan | Leadership's attention is elsewhere | Effort on the hard, unglamorous work slips | An unambiguous internal line on what the plan is |
The target | A buyer exists, and has shown its hand | A higher price if you return; defenses if you don't | A decision on whether you will ever come back |
Lenders | Leverage may be about to change | Tighter terms on debt you already need | Your financing limit, agreed before the work starts |
Competitors and customers | You may be distracted, or for sale | Poached people, wobbling accounts | Talking points for the people who own those relationships |
Who reads a leaked exploration, and what they hear. Illustrative, not a description of any one company's experience. The same five audiences apply to a private company weighing an acquisition, a merger or a sale.
Before you take the banker's call
Owners of private companies tend to think this is a public-company problem. It is worse in a private one. A banker's pitch book circulates; a broker calls three of your competitors to gauge interest; a finance director asks for a data room and the IT team notices. Your leadership team, your top accounts and a rival's sales force usually know before any journalist would.
The fix isn't to stop looking. It is to treat exploration as a decision with a cost, made with the same seriousness as the deal it might lead to.
Settle these before the first meeting
Set the bar for looking close to the bar for doing. If you couldn't explain the deal at your next all-hands, don't commission the work.
Write the "why now" sentence. If it only makes sense as a hedge against your own plan, everyone who hears of it will read it that way.
Draft both public answers in advance: the holding line and the denial. Agree which one you will use, and when.
Put the work on a clock. Exploration that runs "in recent months" with no end date is the kind that leaks.
Tell your own team where the boundary is. They should hear what the plan is from you, not what it might be from someone else.
There's a harder test underneath all of this. A leadership team that keeps commissioning big-deal studies while its plan is delivering should ask what it is really unsure about. Sometimes the honest answer is that the plan works but is too slow for the ambitions of the people running it. That is a real problem, and worth naming. It is a board conversation, though, not a banker's mandate.
Starbucks goes into its fourth-quarter report with one fewer option and a plan it has promised, in public, to see through. For a turnaround, that may well be the better position. It just wasn't the one management chose.
Sources and notes. Financial Times report of October 8, 2026, that Starbucks had worked with advisers in recent months on a possible Chipotle proposal, as relayed by Reuters (October 8) and PYMNTS (October 8); the FT did not report whether an approach was made. Market values (Starbucks about $107 billion per LSEG; Chipotle about $41 billion) and the "laser focused" response: Reuters, October 8. Starbucks's October 8 intraday decline and flat close are reported differently across versions of the Reuters story; the "as much as 3%" intraday figure should be checked against exchange data. Starbucks statement of October 12, 2026: Reuters and NBC News, October 12. Closing moves on October 12 (Starbucks +1.7%, Chipotle −3.8%): Vantage Markets (October 13) and TheStreet (October 14). Starbucks Q3 fiscal 2026 results, July 29, 2026 (company release): US comparable sales +7.9%, transactions +4.2%, raised full-year outlook, non-GAAP operating margin 14.4%. Margin two years earlier (16.7%), RBC analyst Logan Reich's comments: Reuters, October 8. Year-to-date share performance and Chipotle's near-halving since Niccol's departure: Reuters, October 12. Chipotle 2025 traffic declines: TheStreet, October 14. "Largest restaurant acquisition on record" reflects the FT's characterization as reported by PYMNTS. UK Takeover Code Rule 2.8 (no-intention-to-bid statements; six-month restriction, subject to exceptions). Figure 1 is illustrative. Corrections welcome.